Here is how to set a financial calendar: list every money date in your year (taxes, bills, renewals, savings transfers), add each one to a digital calendar with a reminder, and schedule short recurring check-ins to review your accounts. The first setup takes about two hours. After that, the calendar does most of the remembering for you.
A financial calendar is one schedule that holds every date your money depends on. It replaces the mental list most people carry around, which tends to fail the week an annual fee posts or an estimated tax payment slips by. This guide shows how to set a financial calendar for a US household, from tax deadlines to paycheck-based bill timing.
What a Financial Calendar Includes
Think of your dates in three groups. Fixed dates never move, like the federal tax filing deadline. Floating dates shift with your life, like a lease renewal or a car registration. Review dates are ones you invent, like a monthly budget check.
Most people track only the first group, which is why late fees and missed opportunities keep happening. The third group does the most work, because it forces decisions on a schedule instead of in a panic.
Step 1: Gather Every Date Your Money Touches
Start by collecting the paperwork and logins you already have. You are hunting for any date that triggers a payment, a deadline, or a decision. Here is what to pull together:
- Pay dates and the amount that lands in your account each time
- Rent or mortgage due date, plus any grace period
- Credit card statement closing dates and payment due dates
- Insurance renewals for auto, home or renters, and life
- Student loan, auto loan, and personal loan due dates
- Annual fees and subscription renewal dates
- Tax filing and estimated payment dates
- Employer benefits deadlines
Next, scan the last 12 months of card and bank statements for recurring charges. Annual renewals hide best, since they appear only once a year. A streaming bundle that renews every November is easy to forget until the charge hits.
Step 2: Pick a Calendar Tool You Will Open Daily
The best tool is the one you already look at. Google Calendar, Apple Calendar, and Outlook all support recurring events, color coding, and phone alerts. A paper wall calendar also works if it hangs where you walk past it.
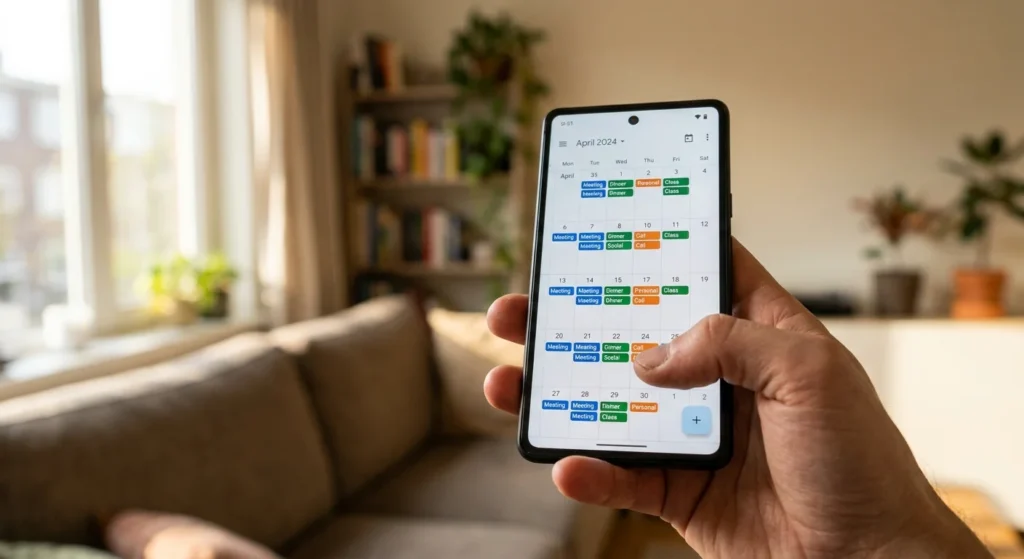
Create a separate calendar called Money so you can switch it on or off. Share it with your spouse or partner if you run the household finances together. Use one color for bills, one for taxes, and one for savings and reviews.
Step 3: Add the Fixed US Tax and Retirement Dates
Tax dates go in first because the penalties are the steepest. Most individual returns are due April 15, and the IRS says a filing extension moves that to October 15 but does not extend the time to pay what you owe. Put both dates in, plus a reminder in early March to gather documents.
Employers must send W-2s and 1099-NEC forms to recipients by January 31, so mark late January as the window when they should arrive. If a form has not shown up by mid-February, contact the issuer.
Estimated Tax Dates for Freelancers and Side Income
If you earn money without withholding, such as freelance pay, rental income, or business profit, add the four estimated tax dates. They fall on April 15, June 15, September 15, and January 15 of the following year, as described in IRS Publication 505. Set the reminder two weeks ahead so you have time to move cash.
Many people also set aside a fixed percentage of every payment the day it arrives. Your CPA or the IRS Tax Withholding Estimator can help you pick a number that fits your situation.
Retirement Contribution Deadline
For 2026, the IRS lists the 401(k) employee deferral limit at $24,500 and the IRA limit at $7,500, per IRS Notice 2025-67. Workers 50 and older can add catch-up contributions on top of those. Payroll contributions have to run through December 31, so a September check on your year-to-date total keeps you from a rushed December adjustment.
IRA contributions work differently. You can make them for a tax year until the filing deadline the following April, so add that date as a second reminder.
Step 4: Map Bills to Your Paychecks
This is the step most guides skip. Instead of sorting bills by due date alone, assign each bill to the paycheck that will pay it. That way you always know which deposit covers which obligation.
Say you are paid on the 1st and 15th. Rent is due the 1st, car insurance the 8th, a credit card on the 20th, and utilities on the 25th. Your calendar should split them like this:
| Paycheck | Covers | Due Dates |
| 1st | Rent, car insurance | 1st, 8th |
| 15th | Credit card, utilities | 20th, 25th |
If a due date lands awkwardly, call the number on your card or loan statement and ask to move it. Many issuers and lenders will change the date if you ask.
Autopay handles the payment, but it does not check your balance. Add a reminder three days before each autopay date so you can confirm the money is there.
Step 5: Schedule Recurring Money Check-Ins
Dates that only record deadlines leave out the decisions. Recurring check-ins turn the calendar into a habit, and they fit into short blocks.
1. Weekly Check-In, 15 Minutes
Review the past week’s transactions, confirm upcoming bills are covered, and flag anything odd on your accounts. Pick a fixed slot, such as Sunday evening.
2. Monthly Check-In, 45 Minutes
Compare actual spending with your budget, move money to savings, and decide on any extra debt payment. This is also the time to log the amounts for next month’s bills.
3. Quarterly Check-In
Review your emergency fund, investment balances, and any estimated tax payment due. Pull your credit reports too. AnnualCreditReport.com offers free reports from Equifax, Experian, and TransUnion, so a quarterly look is easy and costs nothing.
4. Annual Check-In
Once a year, shop insurance, update beneficiaries, review your W-4 withholding, and set savings goals for the new year. January works well, once your tax documents have arrived.
Step 6: Add Open Enrollment and Year-End Dates
Fall brings a cluster of dates that are easy to miss. Employer open enrollment usually runs in the fall, and the choices you make often lock in until the next year. If you have a flexible spending account, check whether your plan has a deadline to spend the balance or allows a carryover.
If you buy health coverage through the marketplace, open enrollment for 2027 plans began on November 1 in most states, and deadlines vary by state, so confirm yours at HealthCare.gov or your state exchange this week.
Year-end also brings charitable giving, any tax moves you plan with your CPA, and required minimum distributions for account owners old enough to be subject to them, which generally must be taken by December 31.
Step 7: Set Reminders With the Right Lead Time
A reminder that arrives on the due date is too late. Match the lead time to how much work the date needs.
- 30 days for annual renewals, so you can compare prices
- 14 days for estimated taxes and large payments
- 3 days for autopay confirmations
- The same morning for small bills you pay by hand
Write each event title so it tells you what to do. “Pay Visa, $240 due” beats “Credit card.” Put the account name and amount in the description, and attach the login link if your calendar app allows it.
Common Mistakes When You Build a Financial Calendar
Most calendars fail for the same few reasons.
- Adding too many alerts, until you start ignoring all of them
- Vague titles that force you to look up the details later
- Skipping the check-ins and tracking only deadlines
- Forgetting to update dates after a move, a job change, or a new loan
- Letting one person hold all the information in a shared household
Fix these by keeping alerts to the dates that matter, writing clear titles, and doing a calendar review every January and July.
A Sample Year at a Glance
This outline shows how the pieces fit across twelve months. Adjust it for your own income and obligations.
| Month | Dates to Add |
| January | W-2 and 1099 forms arrive, fourth-quarter estimated tax due January 15, annual review |
| April | Filing deadline April 15, first-quarter estimated tax, prior-year IRA contribution deadline |
| June | Second-quarter estimated tax due June 15 |
| July | Mid-year withholding and budget review |
| September | Third-quarter estimated tax due September 15, 401(k) year-to-date check |
| October | Extended filing deadline October 15, employer benefits research |
| November and December | Open enrollment, FSA balances, charitable giving, required distributions, final contributions |
A Note on Accuracy
Tax limits, deadlines, and enrollment windows change from year to year. Confirm each date on IRS.gov, HealthCare.gov, or with a licensed CPA or financial planner before you act. This article offers general information and is not tax, legal, or financial advice.
Run the calendar for one month, then adjust any reminders that came too late or too often.