Opening a business account is one of the first financial decisions an LLC owner makes. The wrong choice quietly costs money every month through fees, weak interest, and missed automation. This guide compares the best business bank accounts for an LLC in 2026. It breaks down what each one does well and what to check before you apply.
An LLC separates your personal assets from your business debts, but only if you keep your finances separate too. Courts can pierce the corporate veil when an owner mixes personal and business funds. That removes the liability shield an LLC is built to provide. A dedicated account is the simplest way to keep that line clear.
The Best Business Bank Accounts For an LLC at a Glance
Every LLC has different needs. Cash flow, team size, and how often you deal with international clients all shape which account fits best. The table below compares five strong options across the factors that matter most.
| Provider | Best for | Monthly fee | APY on balances | FDIC coverage |
| Bluevine | Earning interest on idle cash | $0 to $95 | Up to 3.0% | Up to $3 million through partner banks |
| Mercury | Startups and remote founders | $0 | None on standard checking | Up to $5 million through sweep partners |
| Novo | Ecommerce and freelance LLCs | $0 | None | Standard $250,000 |
| Relay | Running several sub-accounts | $0 to $30 | Up to roughly 2.5% on savings sub-accounts | Up to $3 million through partner banks |
| Chase Business Complete Banking | In-person branch access | $15, waivable | None on standard checking | Standard $250,000 |
| U.S. Bank Silver Business Checking | Low-cost traditional banking | $0 | None | Standard $250,000 |
The Best Business Bank Accounts For an LLC in 2026
1. Bluevine: best For Earning Interest
Bluevine pays interest on checking balances instead of forcing you into a separate savings product. The free Standard plan pays a solid rate once you meet a small monthly activity requirement. That could mean a minimum debit card spend or a set amount of incoming deposits. Paid tiers raise both the yield and the balance cap that earns it. Bluevine also skips transaction fees and includes built-in bill pay and invoicing. It suits an LLC that keeps a cash cushion in its operating account instead of sweeping it elsewhere.
2. Mercury: Best For Startups and Remote Founders
Mercury charges no monthly fee and requires no minimum balance. It also extends FDIC coverage well past the standard limit by spreading deposits across partner banks. The application runs fully online and usually takes only a few minutes. You just need your EIN and formation documents ready. Mercury connects directly with QuickBooks, Xero, and Stripe, so bookkeeping stays current without manual entry. It suits an LLC that operates entirely online and has no need for cash deposits or a branch.
3. Novo: Best for Ecommerce and Freelance LLCs
Novo is built around the tools online sellers and service providers already use. It integrates with Shopify, Stripe, and Square. You can track incoming revenue by source without exporting spreadsheets. There is no monthly fee and no minimum balance, and Novo refunds a modest amount of ATM fees each month. The feature set is thinner than Mercury or Bluevine offers. It still fits well as a straightforward account for a single-member or small ecommerce LLC.
4. Relay: Best For Running Several Sub-accounts
Relay lets an LLC open many individual checking accounts under one login. That makes it a natural fit for owners following a profit-first budgeting approach. You can separate tax savings, payroll, and day-to-day cash without opening accounts at different banks. The free Starter plan has no monthly fee and no minimum balance. Paid plans unlock higher yields on savings sub-accounts and extra debit cards for employees. Relay is not a bank itself; a partner institution holds and insures your deposits.
5. Chase Business Complete Banking: Best For Branch Access
Chase remains the strongest choice for an LLC that regularly handles cash. Its nationwide network of branches and ATMs is hard for any digital-first provider to match. The monthly fee is easy to waive with a modest daily balance or a linked Chase credit card. Wire fees and overdraft charges run higher than most online alternatives, though. Chase also offers same-day deposits and card processing tools suited to a retail or service business with foot traffic.
6. U.S. Bank Silver Business Checking: Best Low-cost Traditional Account
Some LLCs want a brick-and-mortar bank without premium-tier fees. U.S. Bank’s Silver Business Checking charges no monthly maintenance fee. It also allows a set number of free transactions each month. That makes it a solid fit for a newer LLC with modest transaction volume. You still get the reassurance of a nationally recognized bank and in-branch support when you need it.
What to Look For in a Business Bank Account For Your LLC
Start with the monthly fee and how it gets waived. A minimum balance requirement can tie up cash your LLC would rather use for growth. Next, check wire and ACH fees. A provider that looks free on paper can still charge $25 to $40 per outgoing wire. FDIC coverage matters too, especially once your balance passes the standard $250,000 limit. Several digital providers now spread deposits across partner banks to extend that protection into the millions. If your LLC bills clients abroad or pays international vendors, look for multi-currency support. That keeps you from losing a few percent to conversion markups on every transaction. Finally, weigh how well the account connects to the accounting software and payment processors you already use. An account that requires manual reconciliation adds hours of work every month.
Documents you need to open a business bank account for an LLC
Most providers ask for the same core paperwork, whether you apply online or in person.
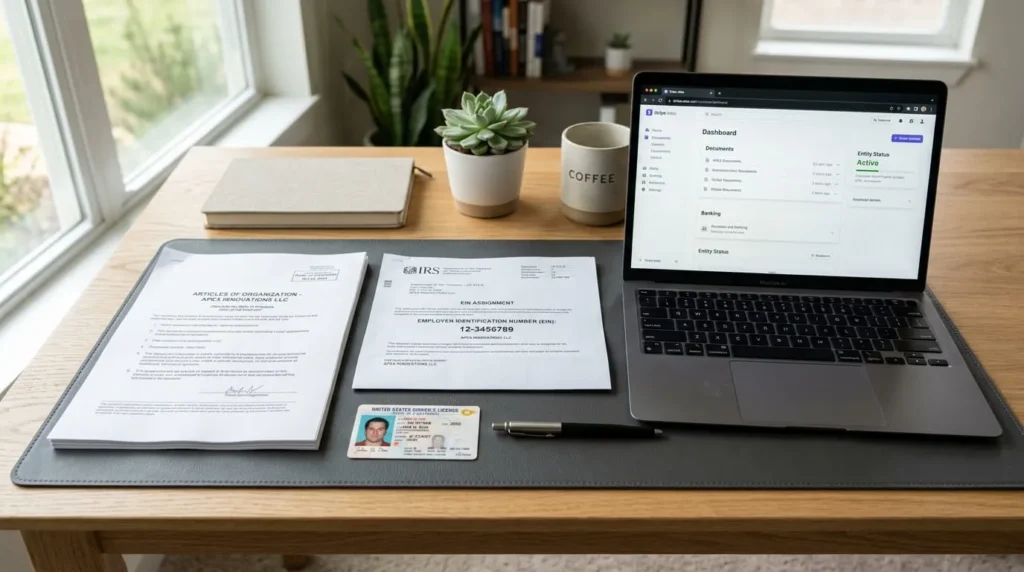
- Your Articles of Organization, proving the state formed your LLC
- An EIN confirmation letter from the IRS
- Government-issued photo identification for every owner with significant equity
- An Operating Agreement, especially if your LLC has more than one member
- A business address, and sometimes proof of an active website or contract
Some providers also ask about your expected monthly deposit volume and whether you plan to send or receive international payments. Opening the right business account is only half the setup — choosing between cash and accrual accounting shapes how transactions from that account get recorded.
How to open a business bank account for your LLC
- Form your LLC with your state and receive your Articles of Organization.
- Apply for a free EIN through the IRS, even if you are the only member.
- Compare providers on fees, FDIC coverage, and the integrations your LLC actually uses.
- Gather your formation documents, ID, and Operating Agreement before you apply.
- Submit your application, fund the account, and connect your accounting software.