Insurance companies make money in two main ways. They collect more in premiums than they pay out in claims and expenses (underwriting profit), and they invest the premiums they hold until claims come due (investment income). Many US insurers also earn fees, commissions, and spread income on products like annuities.
The balance between these streams shifts by insurance type. In 2025, US property and casualty insurers posted a $60.9 billion net underwriting gain, and net investment income rose 9.1 percent to $91.4 billion, according to AM Best. Investment returns were the bigger number.
The Basic Formula Behind Every Insurer
An insurer collects premiums from a large pool of policyholders, pays claims for the few who suffer losses, and keeps the difference. Subtract claims and operating costs from premiums, and you get the underwriting result. Investment income gets added on top.
The model works because of the law of large numbers. Nobody can predict whether one particular house will burn down this year. Across 500,000 houses, the loss rate becomes steady enough that actuaries can price it.
Underwriting Profit: Charging More Than Claims Cost
Underwriting profit is what remains after claims and operating expenses come out of premiums. Operating expenses include agent commissions, marketing, salaries, technology, and the cost of handling claims.
1. What a Combined Ratio Tells You
Insurers track this with the combined ratio, which adds claims losses and expenses and divides the total by premiums earned. A ratio under 100 means an underwriting profit. A ratio over 100 means the insurer paid out more than it collected.
The US property and casualty industry’s combined ratio improved 3.7 points in 2025 and landed in the low 90s, according to AM Best. Catastrophe losses accounted for 7.6 points of that ratio, down from 8.8 points in 2024. Insurers also booked $18.1 billion of favorable reserve development, meaning earlier claim estimates turned out higher than needed.
2. A Simple Example With Numbers
Say an auto insurer collects $1,000 in premium from a policyholder. It pays $680 in claims on average and spends $270 on commissions, overhead, and claims handling. The combined ratio is 95, and the underwriting profit is $50.
Now suppose a bad storm season pushes claims to $780. The combined ratio becomes 105, and the insurer loses $50 on underwriting. That is where investment income comes in.
3. How Insurers Price Risk
Actuaries set rates using claims history, location, driver age, vehicle or home characteristics, coverage limits, and, in states that allow it, credit-based insurance scores. In many states, regulators review rate filings before the new prices take effect.
Underwriters then decide whom to accept. A home in a wildfire zone or a driver with several at-fault accidents may get a much higher price or a denial. That selectivity protects the loss ratio.
Investment Income: The Float Behind the Business
Premiums arrive upfront, but claims are paid later. In liability and workers’ compensation lines, payouts can stretch across years. During that gap, the insurer holds the money, called float, and invests it.
In 2025, the industry’s investment income exceeded its entire underwriting gain. Together, the two pushed pre-tax operating income up 43.2 percent to $153.1 billion.
Why Insurers Can Lose on Underwriting and Still Profit
Take an insurer with a combined ratio of 102. It pays out $1.02 for every $1.00 of premium, a 2-cent underwriting loss. If the premium dollar earns more than 2 cents in investment return before it leaves, the company still comes out ahead.
This explains why insurers sometimes price aggressively when competition is fierce. Berkshire Hathaway’s annual shareholder letters have long described insurance float as a low-cost source of investment capital, with GEICO among the units that generate it.
What Insurers Invest In
State laws and capital rules limit how much risk an insurer can take with policyholder money. Portfolios are mostly bonds, with smaller positions in stocks and real estate. When interest rates rise, new bond purchases earn more, which helps explain why investment income has climbed recently.
How Different Types of Insurers Earn Their Profit
1. Auto and Home Insurers
Auto and homeowners policies run six or twelve months, so insurers can reprice quickly. Profit swings on claim frequency, repair costs, and weather. Moody’s reported that the personal auto combined ratio dropped 2.2 points to 86.4 in 2025, as summarized by Carrier Management.
2. Life Insurers
Life insurers take premiums for promises that can last decades. They invest in long-term assets and earn a spread between portfolio returns and what they credit or promise to policyholders. This matters most on annuities and cash-value policies.
They also gain when actual mortality runs better than the assumptions used in pricing. Some policyholders drop permanent policies before a death benefit is paid, and that can add to profit as well.
3. Health Insurers
The Affordable Care Act sets a medical loss ratio, according to HealthCare.gov. Individual and small-group plans must spend at least 80 percent of premiums on medical care and quality improvement, and large-group plans must spend at least 85 percent, or the insurer owes rebates.
That limits margins. The remaining 15 to 20 percent pays for administration, sales, and profit. Health insurers earn by enrolling many people, negotiating provider rates, and controlling administrative costs.
Other Income: Fees, Commissions, and Reinsurance
Smaller streams add up. Many insurers charge installment fees, policy fees, and late-payment fees. Some own agencies, asset management arms, or service companies that earn their own fees. Retirement products such as variable annuities generate fees based on assets.
Reinsurance does not create profit directly. Insurers pay larger companies to take slices of risk, so one hurricane or wildfire season cannot wipe out their capital. Reinsurers are insurers too, earning money the same way through premiums and investments.
How Insurers Protect Their Margins
Deductibles, coverage limits, exclusions, and waiting periods reduce what an insurer pays per claim. A higher deductible also removes many small claims entirely.
Insurers also control who they cover. Several large carriers have limited new homeowners policies or declined to renew in parts of California and Florida, where wildfire and hurricane losses are heavy.
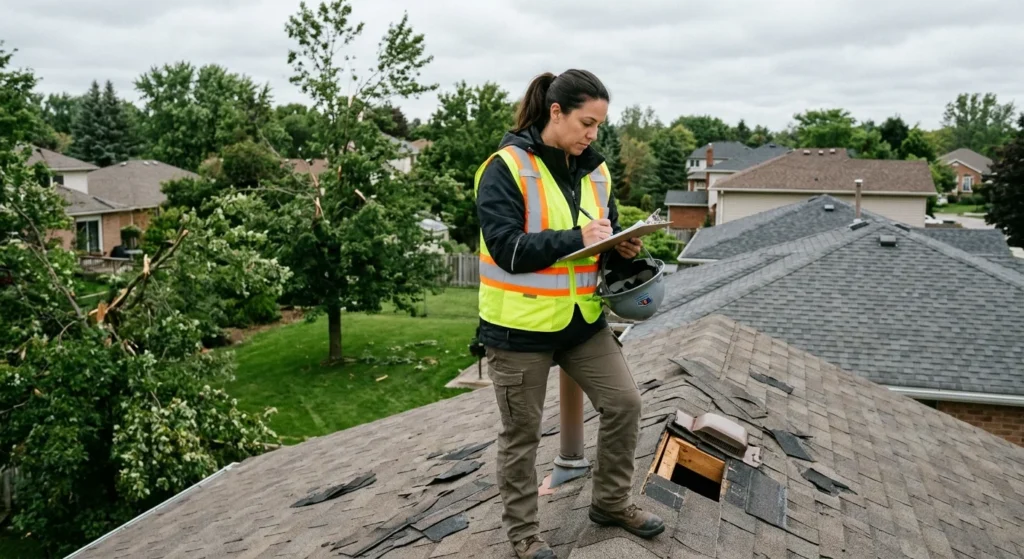
Claims handling is the third lever. Adjusters verify losses, negotiate repair costs, and investigate fraud. Disputes over denied or underpaid claims are common, and state insurance departments accept consumer complaints.
Why Your Premium Can Rise Even When Insurers Are Profitable
Record 2025 results did not bring lower bills. Verisk and the American Property Casualty Insurance Association said the strong underwriting result came from unusually low catastrophe losses, not a basic shift in underlying exposure. Rates reflect expected future claims, not last year’s luck.
Rising repair costs, litigation, and costlier weather push expected claims higher. AM Best has also said that rate trends in most major lines have stabilized or softened, which could pressure underwriting results in 2026.
Because investment income cushions losses, insurers sometimes accept thin underwriting margins in competitive markets. Once those margins disappear, they raise rates sharply. That is why premiums often rise in jumps rather than smooth steps.
What This Means When You Shop for Coverage
Compare quotes from several companies, since each prices risk differently. Raising your deductible shifts small-claim costs to you and can lower your premium. Bundling policies and keeping a clean claims record often reduce price too.
Check an insurer’s financial strength rating from AM Best and its complaint record with your state insurance department. A cheap premium from a weak insurer is a poor trade if it struggles to pay claims. Once you see how insurance companies make money, the pricing and claims decisions behind your policy start to make sense.