A trust fund is a legal arrangement that holds money, property, or other assets on behalf of someone else. Instead of leaving assets directly to a person through a will, you place them into a trust. A trustee then manages and distributes them according to instructions you set. Many people assume a trust fund is reserved for the wealthy, but that isn’t accurate. A trust fund is a container built around a set of rules. It can hold anything from a modest savings account to a family business. Understanding what a trust fund is helps you decide whether it belongs in your own estate planning. This guide breaks down the mechanics, the costs, and where a trust fund actually makes sense.
What Is a Trust Fund, Exactly
People often use “trust” and “trust fund” interchangeably, but they aren’t quite the same thing. A trust is the legal relationship itself, the set of instructions that governs how assets are handled. A trust fund is the actual pool of assets sitting inside that arrangement. Once assets move into a trust, they stop belonging to you personally in a legal sense. They belong to the trust, managed for the benefit of whoever you name.
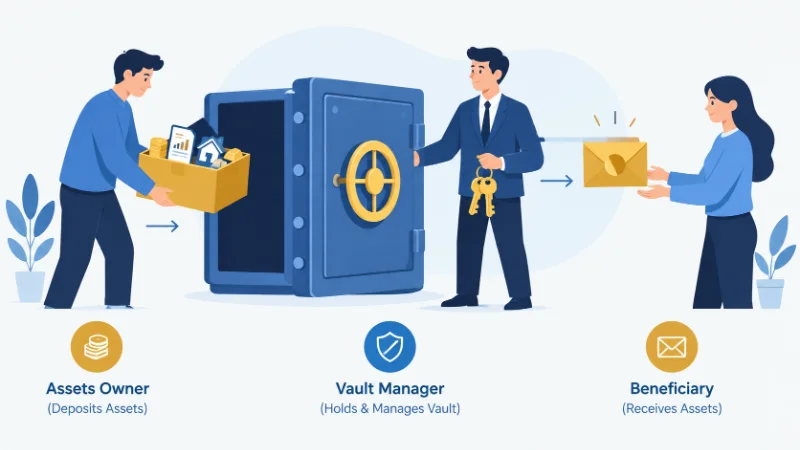
The Three People Who Make a Trust Fund Work
Every trust fund depends on three roles, even if one person fills more than one of them.
The Grantor (or Settlor)
The grantor, also called the settlor or trustor, creates the trust and transfers assets into it. The grantor decides who benefits and under what conditions. With a revocable trust, the grantor typically keeps the right to change these instructions while alive.
The Trustee
The trustee is the person or institution responsible for managing the trust fund according to the grantor’s instructions. This can be a family member, a friend, an attorney, or a bank’s trust department. A trustee has a fiduciary duty, meaning they must act in the beneficiaries’ best interest rather than their own. Poor trustee choices are a common reason trust funds run into disputes.
The Beneficiary
The beneficiary is the person, or group of people, who receives the benefit of the trust fund’s assets. A trust can name one beneficiary or many, and can pay out immediately, on a schedule, or after milestones like turning 25.
How a Trust Fund Actually Works
Setting up a trust fund follows a fairly consistent process. First, an attorney drafts a trust document spelling out the trustee, the beneficiaries, and exactly how distributions happen. Second, you fund the trust by retitling assets, such as bank accounts or real estate, into the trust’s name. This step gets skipped more often than people expect. An unfunded trust offers no real protection, since assets left in your own name still go through probate. Third, the trustee manages those assets, following the document’s instructions, then distributes them to beneficiaries on the schedule you set.
Revocable vs. Irrevocable Trust Funds: Which Type Do You Need?
The biggest decision when setting up a trust fund is whether it should be revocable or irrevocable. A revocable trust, sometimes called a living trust, lets you change the terms, swap beneficiaries, or dissolve it entirely while you’re alive. Because you keep this control, its assets still count as part of your taxable estate. Creditors can generally still reach them too. An irrevocable trust works differently. Once you transfer assets into it, you generally give up the right to change the terms or reclaim the property. In exchange, an irrevocable trust fund removes those assets from your taxable estate and shields them from most creditor claims and lawsuits. Most people start with a revocable trust for flexibility, then add an irrevocable trust later if tax exposure becomes a bigger priority.
Common Types of Trust Funds
Beyond the revocable and irrevocable split, trust funds come in several specialized forms.
Living trust. Created and funded while alive, mainly to avoid probate and manage assets during incapacity.
Testamentary trust. Created through a will and only takes effect after death, so it still requires probate.
Spendthrift trust. Restricts how quickly a beneficiary can access funds, protecting someone who struggles with money management.
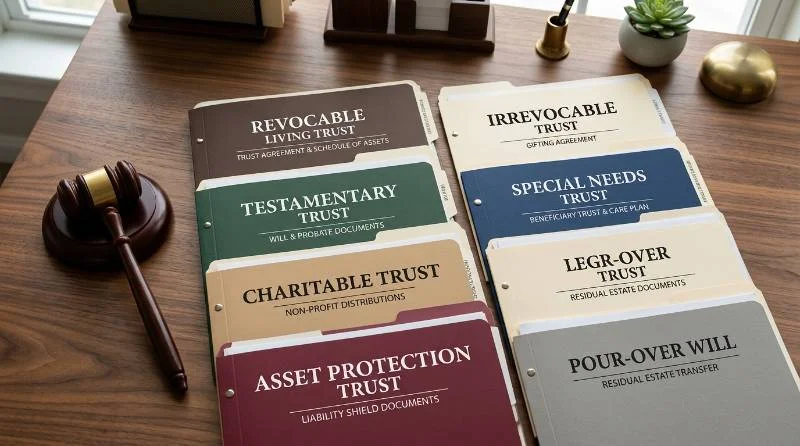
Special needs trust. Preserves a beneficiary’s eligibility for Medicaid or Supplemental Security Income while still adding financial support.
Charitable trust. Directs some or all assets to a charity, often with tax advantages for the grantor.
Generation-skipping trust. Passes assets to grandchildren, bypassing the grantor’s children to reduce taxes across generations.
Marital trust. Provides income for a surviving spouse while controlling where remaining assets eventually go.
What Can You Put Into a Trust Fund?
A trust fund can hold nearly any asset you legally own. Common examples include cash, investment portfolios, real estate, life insurance, business interests, and valuable personal property. Retirement accounts require special handling, since moving them into a trust can trigger unwanted tax consequences. An estate planning attorney can tell you which assets belong in the trust and which work better as a simple beneficiary designation.
The Real Benefits of a Trust Fund
The phrase “trust fund kid” carries a stereotype of inherited wealth and easy living, but that undersells what trust funds actually do. Probate avoidance is one practical benefit. Assets in a properly funded trust bypass probate court entirely, saving beneficiaries months of delay and real money. Privacy is another advantage, since a will becomes public record once probate begins, while a trust fund generally stays private. Trust funds also let you control timing. A beneficiary who isn’t ready to manage a large sum doesn’t have to receive it all at once. This matters most when the beneficiary is a minor or has a disability. An irrevocable trust fund can protect assets from lawsuits, divorce settlements, and creditors in ways a bank account never could. Finally, a trust fund can specify what happens to your assets if you become incapacitated. That way, a court doesn’t have to appoint someone to manage your finances.
How Much Does It Cost to Set Up a Trust Fund?
A straightforward revocable trust drafted by an attorney typically costs between 1,000 and 3,000 dollars. Complex trusts or high value estates run higher. Online template services advertise trusts for a few hundred dollars, but they carry real risk. A template that ignores your state’s trust laws can leave your family right back in probate court. So can one you fail to fund correctly. Beyond setup, some trusts carry ongoing costs. Naming a bank or professional trustee usually means an annual fee, often a percentage of the assets managed.
How Are Trust Funds Taxed?
Tax treatment depends on the type of trust. A revocable trust is treated as an extension of the grantor. All income it generates gets reported on the grantor’s personal return. An irrevocable trust typically becomes its own taxpayer, filing a separate return and paying tax on income it retains. Trusts hit the highest federal income tax bracket at a much lower income level than individuals do. That is why trustees often distribute income to beneficiaries rather than let it accumulate. When income passes through, beneficiaries pay tax on it at their own rate instead. Estate tax is separate and only applies above the federal exemption threshold, high enough that most families never owe it. Review your situation with a tax professional before finalizing anything.
Do You Need to Be Wealthy to Set One Up?
No. There’s no minimum dollar amount required to create a trust fund. Anyone with a home, a savings account, or a life insurance policy can benefit from one. What matters more than net worth is whether your situation involves complexity a trust can solve. That includes minor children, a blended family, or a beneficiary with special needs.
Trust Fund vs. Will: Which One Do You Actually Need?
A will only takes effect after you die, and any assets it covers must pass through probate court first. A trust fund can start working immediately and manage your affairs if you become incapacitated. It also lets assets pass to beneficiaries without court involvement. Even so, a trust fund rarely replaces a will completely. You still need a will to name a guardian for minor children. You also need one to catch stray assets you forgot to retitle, often handled through a pour-over will. Most solid estate plans use both together, each covering what the other can’t.
When a Trust Fund Might Not Be the Right Choice
A trust fund isn’t automatically right for everyone. If your estate is small and your state offers a fast, low-cost probate process, the ongoing administrative work might outweigh the benefits. Retirement accounts and life insurance already pass outside probate through beneficiary designations, so a trust fund adds little value there. Without a trustee you actually trust, a poorly managed trust fund can create more family conflict than a plain will would.
How to Set Up a Trust Fund
Start by deciding what the trust fund should accomplish, whether that’s avoiding probate, protecting a beneficiary, or cutting estate tax exposure. Choose a trustee you trust, and name a successor trustee in case your first choice can’t serve. Work with an estate planning attorney familiar with your state’s trust laws to draft the document. Once it’s signed, fund the trust by retitling accounts, deeds, and other property into the trust’s name. Review it every few years, or after major life events like marriage, divorce, or the birth of a child.